Wedding vs House Deposit in the UK: Financial Opportunity Cost & Budget Balancing
Direct Answer: Deciding between funding a wedding and saving a first-time buyer house deposit is one of the most critical financial trade-offs UK couples face. While the average UK wedding costs over £20,000 for a single day of celebration, allocating that capital toward a property deposit builds long-term home equity and avoids substantial compound opportunity costs. Balancing your budget between romantic milestones and property ownership requires evaluating mortgage interest rates, house price growth, and realistic dual savings strategies.
How Does Average UK Wedding Cost Compare to a First-Time Buyer House Deposit?
The financial choice between a wedding and a property deposit in the UK highlights a stark contrast between short-term celebratory expense and long-term asset accumulation.
- Average UK Wedding Cost: £20,600 – £23,990 (including venue rental, catering, photography, attire, and entertainment).
- Average UK First-Time Buyer House Deposit (10%): £28,500 – £35,000 based on an average UK home price of £285,000 (reaching £80,000+ in London and the South East).
- Minimum UK Mortgage Deposit (5%): £14,250 on a £285,000 starter home.
What Is the Compound Opportunity Cost of Spending House Savings on a Single Day?
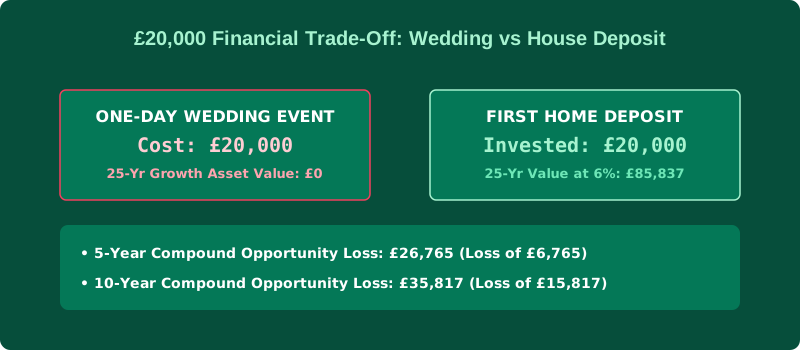
Allocating £20,000 of liquid savings to a one-day wedding event carries a hidden financial burden known as compound opportunity cost. Money spent on wedding expenses can no longer compound inside tax-free stocks and shares ISAs or generate equity through property capital appreciation.
Compound Growth Formula: Future Value = Principal × (1 + Annual Return)^Years
If £20,000 is invested in a property deposit or index fund earning an average 6% net annual return:
- In 5 Years: The initial £20,000 grows to £26,765 (a loss of £6,765).
- In 10 Years: The initial £20,000 grows to £35,817 (a loss of £15,817).
- In 25 Years: The initial £20,000 grows to £85,837 (a loss of £65,837).
How Can Couples Split Budget Between a Wedding and a Property Deposit?
Couples do not necessarily have to abandon their wedding dreams to buy a home. Utilizing structured financial compromises allows partners to celebrate while securing property keys.
- The 70/30 Split Allocation Strategy: Allocate 70% of monthly combined savings to a high-yield Lifetime ISA (LISA) for your house deposit, while directing the remaining 30% to a separate wedding budget account.
- Micro-Wedding + Future Anniversary Party: Host an intimate UK registry office ceremony (£150–£500) with immediate family, then save the large £20,000 celebration for a 5-year anniversary party.
- Lifetime ISA Government Bonus Boost: First-time buyers aged 18–39 can deposit up to £4,000 per year into a Lifetime ISA (LISA). The UK government adds a 25% bonus (up to £1,000 free per year per person).